Renting for 30 Years Could Make You Richer Than Buying a House in America. Here's the Math!
Renting for 30 Years Could Make You Richer Than Buying a House in America. Here's the Math!
For many Nepalis living in America, buying a house is considered a major achievement. We often hear people say, “Why waste money on rent when you could pay a mortgage instead?”
But what if renting for 30 years could actually leave you with more money?
Let's look at a simple example.
Two families, two choices
Imagine two families living in similar homes.
Family A buys a $500,000 house. They put $100,000 down and take a 30-year mortgage at 7.4% interest.
Family B rents a similar house for $2,500 per month. Instead of buying, they invest the money they save.
Here's what their monthly expenses look like in the first year:
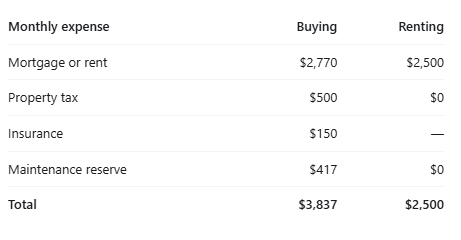
Family B saves approximately $1,337 per month initially.
But here's the secret: Family B doesn't spend that extra money. They invest it.
What happens after 30 years?
Let's assume the house increases in value by 3% annually, rent increases by 3% annually, and investments earn an average of 6% per year.
The renter invests the $115,000 that would otherwise have gone toward the down payment and closing costs, plus the monthly savings. Both families invest any savings when their housing costs are lower.
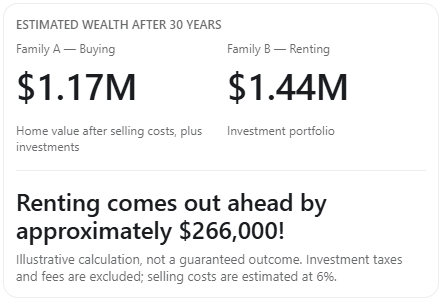
How is this possible?
The homeowner spends money on mortgage interest, property taxes, insurance, and maintenance for 30 years.
The renter, meanwhile, puts the money they save into investments. Over time, those investments can grow through compound returns—earning returns on earlier returns.
And because the renter starts investing a large amount immediately, that money has decades to grow.
But isn't owning a house better?
Owning a home has real advantages. After 30 years, Family A has a fully paid-off house and no more mortgage payments.
Family B still needs to pay rent.
However, Family B has a larger investment portfolio under this example, which could help pay future rent or other living expenses.
The important difference is that buying builds wealth through property ownership, while renting can build wealth through investing.
Neither strategy guarantees a better result. If home prices grow faster, investments perform poorly, or rent increases more rapidly, buying could win.
The bottom line
Buying a house isn't always the smartest financial decision, and renting isn't necessarily throwing money away.
If you rent a reasonably priced home and consistently invest the money you save, you could end up wealthier after 30 years than someone who buys.
But there's one catch: you must actually invest the savings instead of spending them.
Before committing to a 30-year mortgage, ask yourself: Am I buying a house because the numbers make sense, or simply because everyone around me is buying one?
Sources and further reading
- Consumer Financial Protection Bureau — Homebuying Guide
- Freddie Mac — Mortgage Rate Survey
- SEC Investor.gov — Compound Interest Calculator
Note: This article uses a hypothetical $500,000 home, a 7.4% mortgage rate, 3% annual home appreciation and rent increases, and 6% investment returns. Actual results vary with market conditions, taxes, fees, and personal circumstances.


-
 Basement USD 1,050.00Manassas, VA ·
-
 Basement for rent in manassas USD 1,200.00Manassas, VA ·
-
 Private basement for Rent USD 1,300.00Gaithersburg, MD ·
-
 Room USD 800.00Everett, MA ·
-
 Malden, MA ·