H1 B Nepalis
this is for Nepalese Consultant who are working on H1B or looking for H1B. Please Don't advertise here.
BetterNepal · Dec 26, 2009 11:12 PM · 1,711 views
It is that time of year again. Time to plan for your 2009 tax year and maximize your tax refund. Some of you have been contacting us for last minute saving tips and hence to the benefit of everyone we are sending this E-Mail. To that extent we enclose the following: Last-Minute tax tips Tax law changes for 2009 We look forward to seeing you all again for filing your 2009 taxes! Last-Minute Tax Tips Some last-minute tax-reduction planning tips. Here are a few suggestions Contributions to your favorite charity If you have appreciated stock that you've held for more than one year, you might want to keep the cash in your pocket and donate the stock. You'll avoid paying tax on the appreciation, but will still be able to deduct the full value of the stock. You win, your charity wins, and the only loser is Uncle Sam. If you still love the stock and want to maintain a position in the shares after your charitable contribution, you can simply buy new shares in the company. Deadline for this is December 31, 2009. And don't forget about the contributions that you will make by check! Remember that you need to have the check written and given to the charity (or at least mailed out) before the end of the year in order for this deduction to "stick." It matters not that the charity may not actually cash the check until the next year. The key is that you deliver it to the charity before the end of the year. It is a 2009 deduction if postmarked December 31, 2009 or earlier. Donate in Kind These donations are tax deductible. You may consider donating clothes or old stuff, furniture, computer etc before 12/31 and get an additional deduction for donations. Make sure you create a list of items donated and pick up a receipt from the charity. Attach the receipt to your list. I prefer you not write on the receipt because frequently the donor undervalues the value of the donation Use your credit card If you have year-end deductible expenses (such as business expenses, medical expenses, charity, rental expense, miscellaneous itemized deductions, or virtually any allowable deduction), you can use your credit card to make the purchase this year, take the deduction this year, and pay your credit card bill next year. You see, when you pay with a credit card, the IRS considers the expense deductible in the year that the charge is incurred, not necessarily when you pay the credit card charge. In fact, going back to the first tip, you can even find charitable organizations that accept credit cards for charitable contributions. If you have the right credit card, you can receive a 30-day "float" that amounts to an interest-free use of the bank's money if you pay it off when the bill comes. Prepay your state and/or local taxes this includes property tax If you believe that your tax bracket next year will be no higher than this year, and you won't be bothered by any Alternative Minimum Tax issues, consider making those state/local tax payments before the end of this year. After all, you're going to owe the money anyway, right? So why not make those payments before December 31 and take the federal tax deduction this year? You might think that this strategy only applies to people who have fourth-quarter estimated tax payments to make in January, but it really doesn't. If you are a W-2 wage earner and expect a state/local tax balance due, even you can use a state/local prepayment voucher and make your tax payment before the end of the year. All you need is a December 31 postmark. (But beware of AMT, although many of you will not be impacted by this you may be if you have huge stock options, exercised but not sold or have itemized deductions for AMT disqualified purposes like Taxes paid and Miscellaneous deductions. If you are in the AMT zone, prepaying your state taxes will not result in any additional deduction for Federal taxes but may help with state taxes.) Prepay your Mortgage Consider making your January Mortgage payment on December 31. Prepay your tax preparer or prepay your legal fees! Fees are deductible in the year they are paid. If you haven’t already paid your tax preparation fee for 2008 tax preparation, make sure your check is dated Dec 31, 2009 and pay it before the yearend. Also you can prepay your 2009 tax preparation fees. Same rules apply to legal and other professional fees Match up your 401(k) contributions As you know, there are maximum limits to 401(k) contributions each year. Generally, your 401(k) contributions must be made throughout the year, but did you know that some 401(k) plans allow for "catch-up" contributions in December if your contribution level is less than the maximum allowed? Using your December bonus to fund the balance of your 401(k), when allowed, might be a good way to dodge some current taxes. If your employer matches some of your catch-up contributions, you're in even better shape. Not all 401(k) plans allow for this provision, so check with your company's benefits administrator. If you are not sheltering the maximum amount in your 401K talk to me at tax time to understand what you may be losing. Capital Gains You can deduct up to $3000 of losses per year. If you have realized gains you could sell stocks you are holding that have paper losses and convert these to actual losses. You can then use these losses to offset real realized gains plus you could sell stocks to get you a net loss of $3000 (the maximum loss allowed). Why pay taxes when you don’t have to! Remember you can’t buy back stocks sold at a loss before 30 days (wash sales rules), although you could buy options in these stocks. If you have realized losses in excess of $3,000 these can be carried forward. Deduction planning This goes hand-in-glove with income planning. If you believe that your marginal tax rate will be greater this year than it will be next year, accelerate deductions into this year's tax return. If you believe that the opposite will be true, then defer deductions into next year. If deduction planning works for you, and you are a cash-basis taxpayer (which virtually all of us are), please remember these important deduction tips: 1. An expense is only deductible in the year in which it is actually paid. (This is especially important for people trying to "bunch" their deductions into a specific tax year. Remember that you can't bunch expenses paid in different years. 2. If you use a credit card to pay expenses (such as last-minute charitable contributions, medical expenses, business expenses, etc.), the IRS considers the expense deductible in the year that the charge is incurred, not in the year that the credit card bill is paid. So consider using your credit card for those last-minute deductible purchases, services, and charitable contributions. 3. If you make a payment by check, make sure that it is dated and mailed before the end of the year. It's not important whether the check actually clears the bank by the end of the year, just that you made the payment before the end of the year. 4. Remember that a mere promise to pay (making a pledge for a charitable contribution, for example) doesn't constitute an actual payment and is, therefore, not deductible until the year actually paid. Business Owners or Business related expenses If you have a business or business related expenses, consider buying your capital assets by year-end, make sure you charge it or pay by check. Section 179 allows you to expense (i.e., deduct currently) purchases of business assets and property that you would otherwise be required to depreciate and deduct over a number of years. The total cost of Section 179 property can be immediately deducted is $250,000 for 2009. see tax law changes Deductions and credits for non-itemizers Just because you don't itemize your deductions doesn't mean that there aren't deductions and credits out there for you to use. Alimony paid, pension plan deductions (Keogh, SEP, SIMPLE, IRA, etc.), student-loan interest, job-related moving expenses, medical insurance for the self-employed, and deductions for self-employment taxes are all available to you -- regardless of whether you itemize deductions. This is true also for the many credits available to you even if you don't itemize your deductions. Some of the most popular credits include the Child Tax Credit, the Hope and Lifetime Learning Credit, and the Dependent Care Credit. Note: Simple IRA accounts need to be funded by January 15th to qualify as a 2009 deduction, so make sure you fund by then. Questions? email or call Tax Law Changes For 2009 Tax Credit of Up to $8,000 for First-Time Homebuyers and $6,500 for Existing Homeowners The Congress and the Obama Administration have extended and expanded the wildly popular 2008 first-time homebuyer tax credit. Now, existing homebuyers are eligible to receive a tax credit of up to $6,500 if they buy a replacement home by June 30, 2010. In addition, the income limits have been increased, making even more people eligible for these credits. If you purchased a primary residence in 2009 before December 1, 2009, and are a “first-time” homebuyer, you can qualify for a tax credit equal to 10 percent of up to $80,000 of the purchase price. To be eligible, you must not have owned a residence in the United States in the previous three years. The credit is refundable to the extent it exceeds your regular tax liability, which means that if it more than offsets your tax liability, you’ll get a refund check. But it does not offset the Alternative Minimum Tax. You can even elect to claim the credit for a 2009 home purchase on your 2008 tax return. (If you filed for 2008 before buying, but before the December 1, 2009, deadline, you can claim your credit by filing an amended return using Form 1040X. Doing so will guarantee you a refund check.) The credit for 2009 purchases generally doesn’t have to be paid back. But you will have to repay it if you sell the house within three years of the date you bought it. In November 2009, the program was broadened to include existing homeowners, meaning those who have lived in the same principal residence for any five-consecutive-year period during the past eight years. Homeowners are eligible for a credit of up to $6,500 if they buy a replacement home to use as their principal residence. They are not required to sell or dispose of their current home, but the new home must become their principal residence. To be eligible, homebuyers must buy, or enter into a binding contract to buy, a replacement principal residence after Nov. 6, 2009, and on or before April 30, 2010, and close on the home by June 30, 2010. In addition, income limits were expanded from earlier versions of the credit. Homebuyers who file as single or head-of-household taxpayers can claim the full credit if their modified adjusted gross income (MAGI) is less than $125,000. For married couples filing a joint return, the combined income limit is $225,000. Single or head-of-household taxpayers who earn between $125,000 and $145,000, and married couples who earn between $225,000 and $245,000 are eligible to receive a partial credit. The credit is not available for single taxpayers whose MAGI is greater than $145,000 and married couples with a MAGI over $245,000. Also, homes costing more than $800,000 are not eligible for the credit. Indexed Tax Brackets Thanks at least in part to the increase in federal spending and the federal budget deficit in the past few years, the 10 percent, 15 percent, 25 percent, 28 percent, 33 percent and 35 percent tax brackets all kick in at more than 4 percent higher levels of income than in 2008 Educators' Deduction Educators may deduct up to $250 of classroom supplies that they purchased with their own funds. This deduction is scheduled to end after 2009. Kiddie Tax In 2009, a child's unearned income over $1,900, such as gains and dividends, is taxed at the parents' marginal rate until the year the child is age 19, or age 24 for full-time students whose earned income is less than half their support. Estate Tax Exemption For 2009, the federal estate tax exemption is $3,500,000. Exemptions for the Alternative Minimum Tax (AMT) For 2009, the exemption levels rise to $70,950 for married couples filing jointly, $46,700 for singles and heads of household, and $35,475 for married couples filing separately. Otherwise, about 28 million filers would have been added to the AMT rolls. Congress is likely to act again to prevent this from happening for the 2010 tax year. Also, interest on private-activity bonds issued in 2009 and 2010 is exempt from the Alternative Minimum Tax. Income Earned Abroad The maximum foreign earned income exclusion is increased to $91,400, up fom $87,600 in 2008. Personal Exemptions For 2009, each personal exemption is $3,650, up by $150 Personal exemptions are reduced by 2% for each $2,500 of adjusted gross income over $250,200 for MFJ (married filing jointly), $208,500 for HOH (heads of household) and $166,800 for singles, but the reduction cannot exceed $1,217 per exemption Higher Standard Deductions For 2009, the standard deduction is as follows: For married couples $11,400, up by $500. For single filers, $5,700 in 2009, up by $250 Head of household $8,350 up by $350. Non-itemizers who pay real estate taxes can now claim up to $1,000 of property taxes paid for MFJ & $500 for Single. Section 179 Expense Deduction The maximum amount of equipment placed in service in 2009 stays at $250,000. Tax-free Parking for Employees Starting in 2009, firms can pay $230 a month for tax free transit passes or parking for employees. Tax Credit for College Tuition For 2009 and 2010, the Hope credit is replaced by a new credit of up to $2,500 per student a year for four years of college, not just the first two years. It now also covers the cost of books and begins to phase out at $80,000 of adjusted gross income for single filers and $160,000 for joint filers. If the credit is more than your income tax liability, 40% of it is refundable. Also, the full credit is allowed against the alternative minimum tax. Child Tax Credit If the credit exceeds the filer’s tax liability, all or part of the credit will be refunded if the filer earns more than $3,000 in 2009 and 2010. Earned Income Tax Credit Applies to income of less than 40K so it doesn’t apply to most of you Higher Income Limits for Deductible IRAs and for Roth IRAs If you are covered by a retirement plan at work, you can take a full or partial IRA deduction in 2009 dependent upon income levels per amounts listed below IRA Type Single Roth IRA$105,000 – $120,000 Traditional IRA$55,000 – $65,000 Married Filing Jointly $166,000 – $176,000 Traditional $89,000 – $109,000 Increased Contribution Limit for 401(k) Plans The maximum employee contribution rises to $16,500 Workers age 50 and older in 2009 can put in an additional $5,500. SEP and profit-sharing plan limit of $49,000 (up from $46,000). Higher Annual Gift Tax Exemption For 2009, you can give any individual up to $13,000 without owing any gift tax, Credit for Residential Energy-efficient Property The credit for 30% of the cost of installing solar water heating equipment, solar electric equipment, geothermal heat pumps or small wind turbines in your primary residence or a second home is no longer limited to $2,000 after 2008. But the credit for fuel cell property still cannot exceed $500 per half-kilowatt capacity. Credit for Energy-saving Home Improvements The old 10% tax credit of the cost of energy saving home improvements is increased to 30% for 2009 and 2010, up to a maximum of $1,500 in the two-year period. It applies to skylights, windows, outside doors, biomass fuel stoves and high-efficiency furnaces, water heaters and central air conditioners. Converting a Second Home to a Primary Home If you convert a second home into a principal residence after 2008, you may not be able to exclude all of your gain. A portion of the gain on a subsequent sale of the home will be ineligible for the home-sale exclusion of up to $500,000, even if the seller meets the two-year ownership and use tests. Partial Exclusion for Unemployment Benefits For 2009, the first $2,400 of unemployment benefits you received is tax free. College Savings Plans Beginning in 2009, 529 plans can be tapped tax free to pay for a computer or Internet access. Lower Mileage Rates The IRS lowered the standard mileage rates for the business use of vehicles. Beginning on Jan. 1, 2009, the standard mileage rate is: 55 cents per mile for business miles driven 24 cents per mile driven for medical or moving purposes 14 cents per mile driven in service of charitable organizations Sales Tax Deduction for New Vehicles Buyers of new vehicles can deduct the sales tax paid on the purchase, even if they don’t claim sales taxes as itemized deductions. They can add the tax they pay to their standard deduction. This break applies to new cars, motor homes, light trucks and motorcycles purchased after February 16, 2009 and before January 1, 2010. Sales tax paid on the first $49,500 of cost qualifies. The benefit begins phasing out for married couples with AGI over $250,000 and singles with Adjusted Gross Income over $125,000. It is completely gone for single filers with Adjusted Gross Income of $135,000 or more, or joint filers with AGI of at least $260,000. Increased Deductions for Health Savings Accounts (HSAs) You can contribute more in 2009 to business HSAs, with a 100% tax deduction up to a limit of $5,950 for a family, and $3,000 for an individual. RMD’s Suspended For taxpayers age 70½ and older, required minimum distributions from individual retirement accounts and other retirement plans can be skipped without penalty. The same rules apply to heirs of inherited IRAs. U.S. taxpayers working abroad have a higher exclusion tax this year. It is now $91,400. Plug-in Electric Vehicles Credit This modification to the tax credit benefits people who purchase a qualified plug-in electric motor vehicle after 2009. The credit is limited to $7,500, and the amount begins to decrease after the manufacturer sells 200,000 plug-in vehicles. When you purchase a plug-in vehicle, ask the dealer about the credit. You'll claim the credit when you file your 2010 to 2014 tax returns. Payroll Tax Credit For 2009 and 2010, Congress gave workers a credit of 6.2 percent of their earned income, capped at $400 for single filers and $800 for joint filers. For single filers, the credit starts phasing out at $75,000 of Adjusted Gross Income and dries up at $95,000. The phaseout zone for couples is $150,000-$190,000. Employees will get the credit in advance via lower income tax withholding in each paycheck, not as a rebate check. Self-employed taxpayers can reduce their quarterly estimated payments to get an advance benefit from the credit. The exact amount of the payroll tax credit for the year will be calculated on the filers’ tax returns. Recipients of Social Security benefits, Railroad Retirement benefits, Supplemental Security Income or veteran disability pensions get a one-time $250 check for 2009. Federal retirees who don’t receive Social Security payments also get a $250 check. Note: If in doubt, before acting upon these suggestions, check with your tax adviser to make sure the actions suggested are in your best interest.
BetterNepal · Dec 26, 2009 11:20 PM
This conversation is preserved exactly as it was on the original Sajha.com and can't accept new replies.
Start a New DiscussionYou might be interested in...


-
Room Available for Rent USD 850.00Melrose, MA ·
-
One bed room available for rent USD 1,300.00Germantown, MD ·
-
Malden, MA, United States · Reposted Originally posted
-
Big Room with Parking Next to bus stop USD 1,100.00Everett, MA ·
-
Rooms Available for Rent USD 2,700.00Reston, VA ·
-
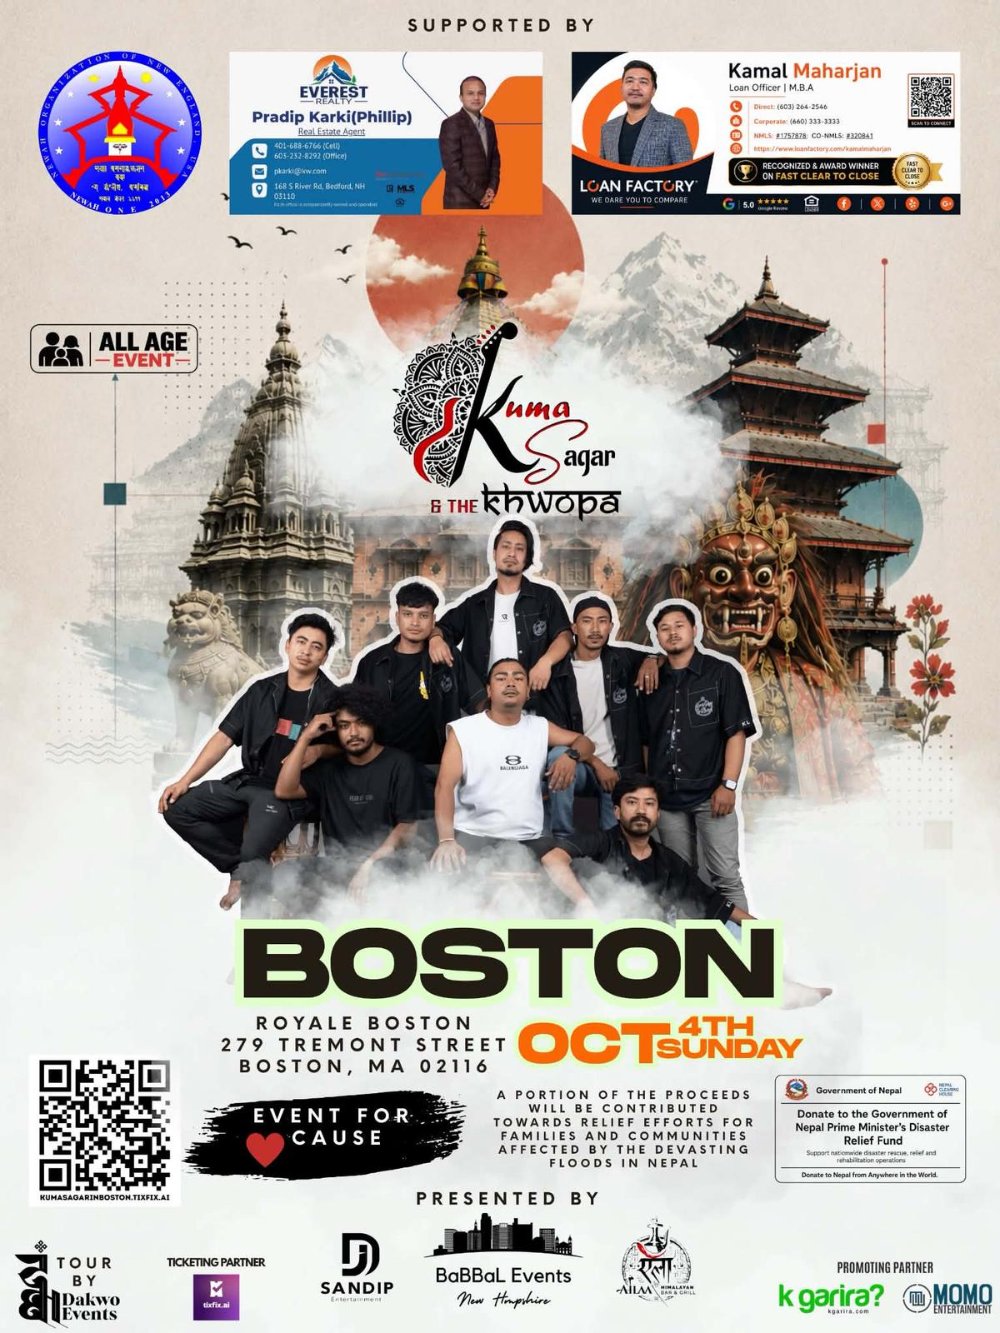 Oct 4, 2026 7:00 PM · Boston / New England · 518 views
-
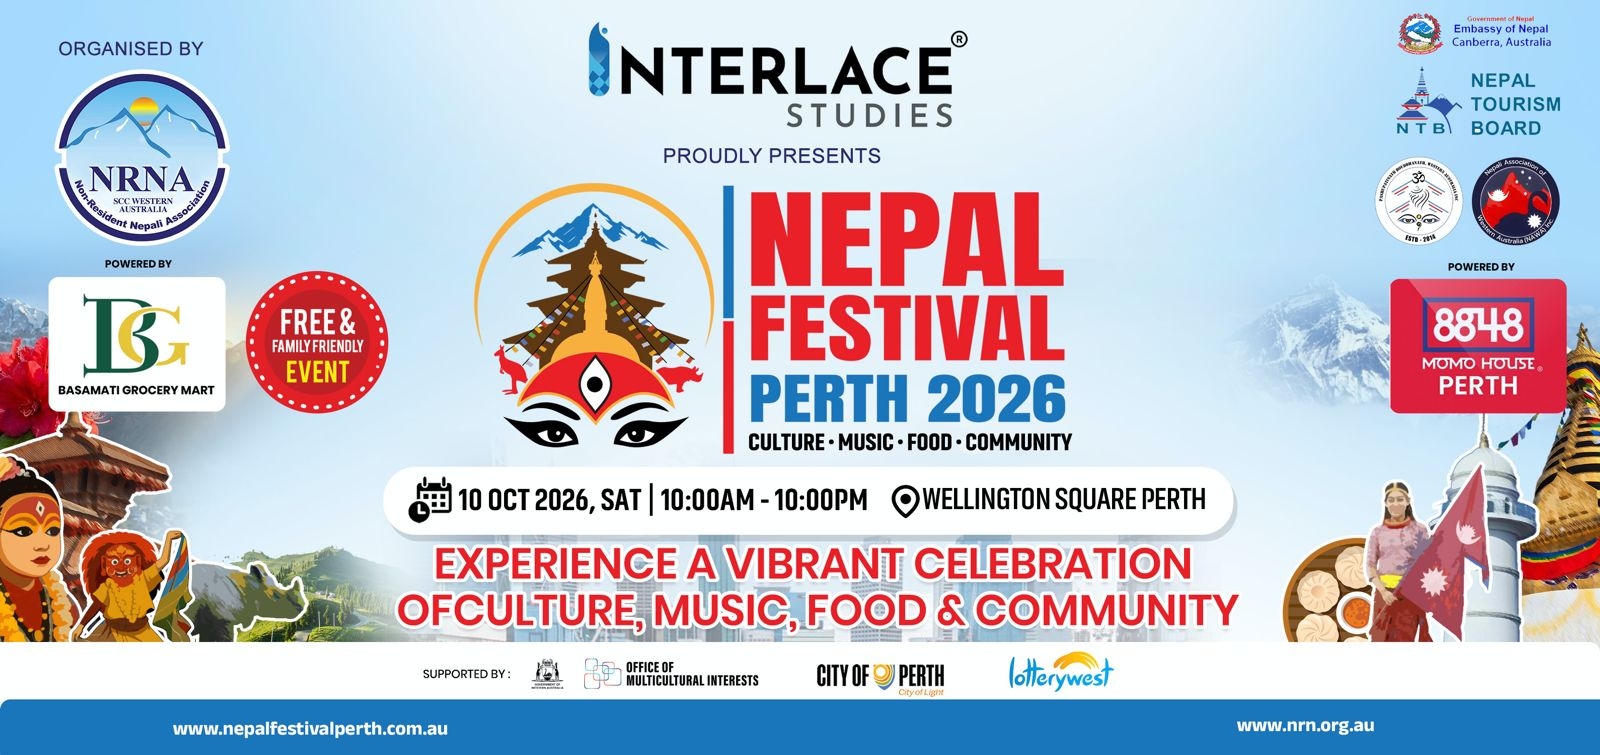 Nepal Festival Perth 2026 FestivalOct 10, 2026 10:00 AM · Perth / Western Australia · 227 views
-
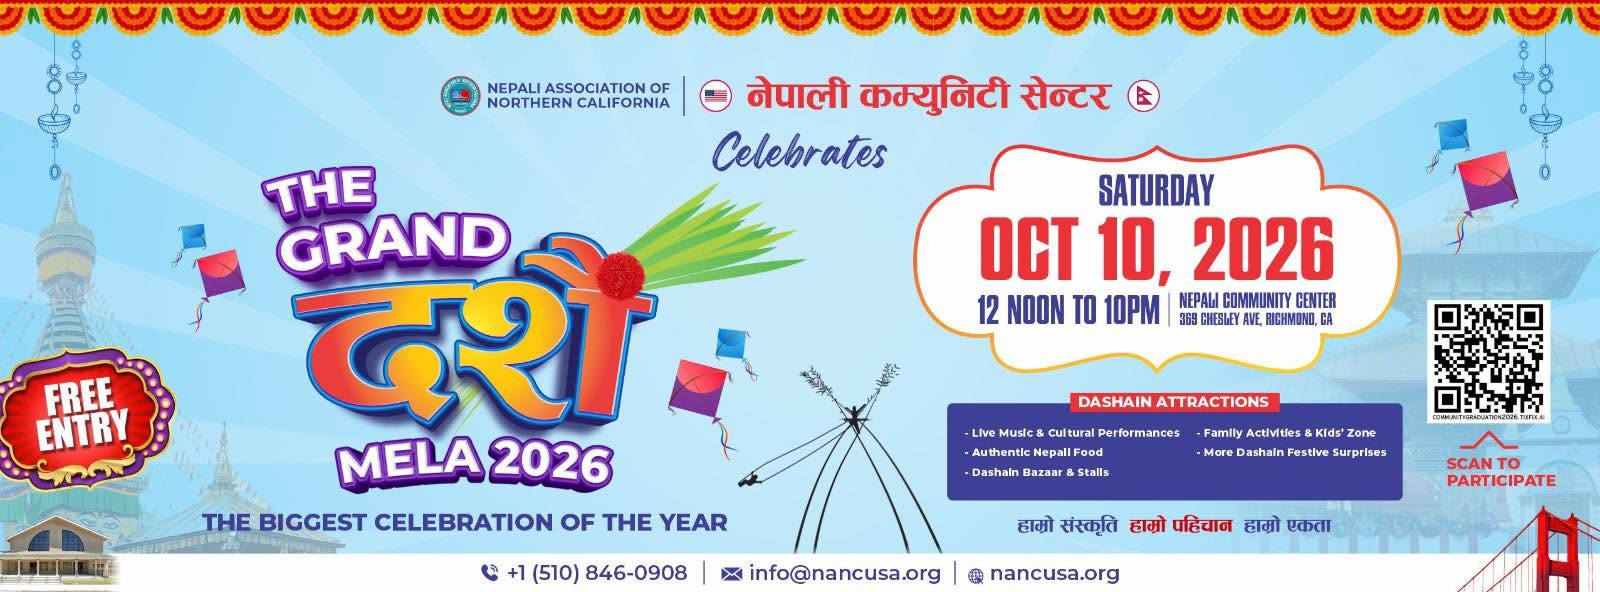 Grand Dashain Mela 2026 FestivalOct 10, 2026 11:00 AM · Bay Area / Northern California · 216 views
-
 Oct 11, 2026 11:00 AM · DMV / Greater Washington · 229 views · Dashain
-
 Dashain Festival Fulpati PartyOct 17, 2026 10:00 PM · Greater London · 190 views · Dashain
-
✓Vianet Communications OtherKathmandu · · 287 views
-
Aama Lama RestaurantMalden, MA · · 244 views
-
Ailaa Himalayan Bar & Grill RestaurantStoneham, MA · · 247 views
-
Ailaa Himalayan Bar & Grill RestaurantBedford, TX · · 222 views
-
Annapurna Curry & Sekuwa House RestaurantManchester, NH · · 225 views